
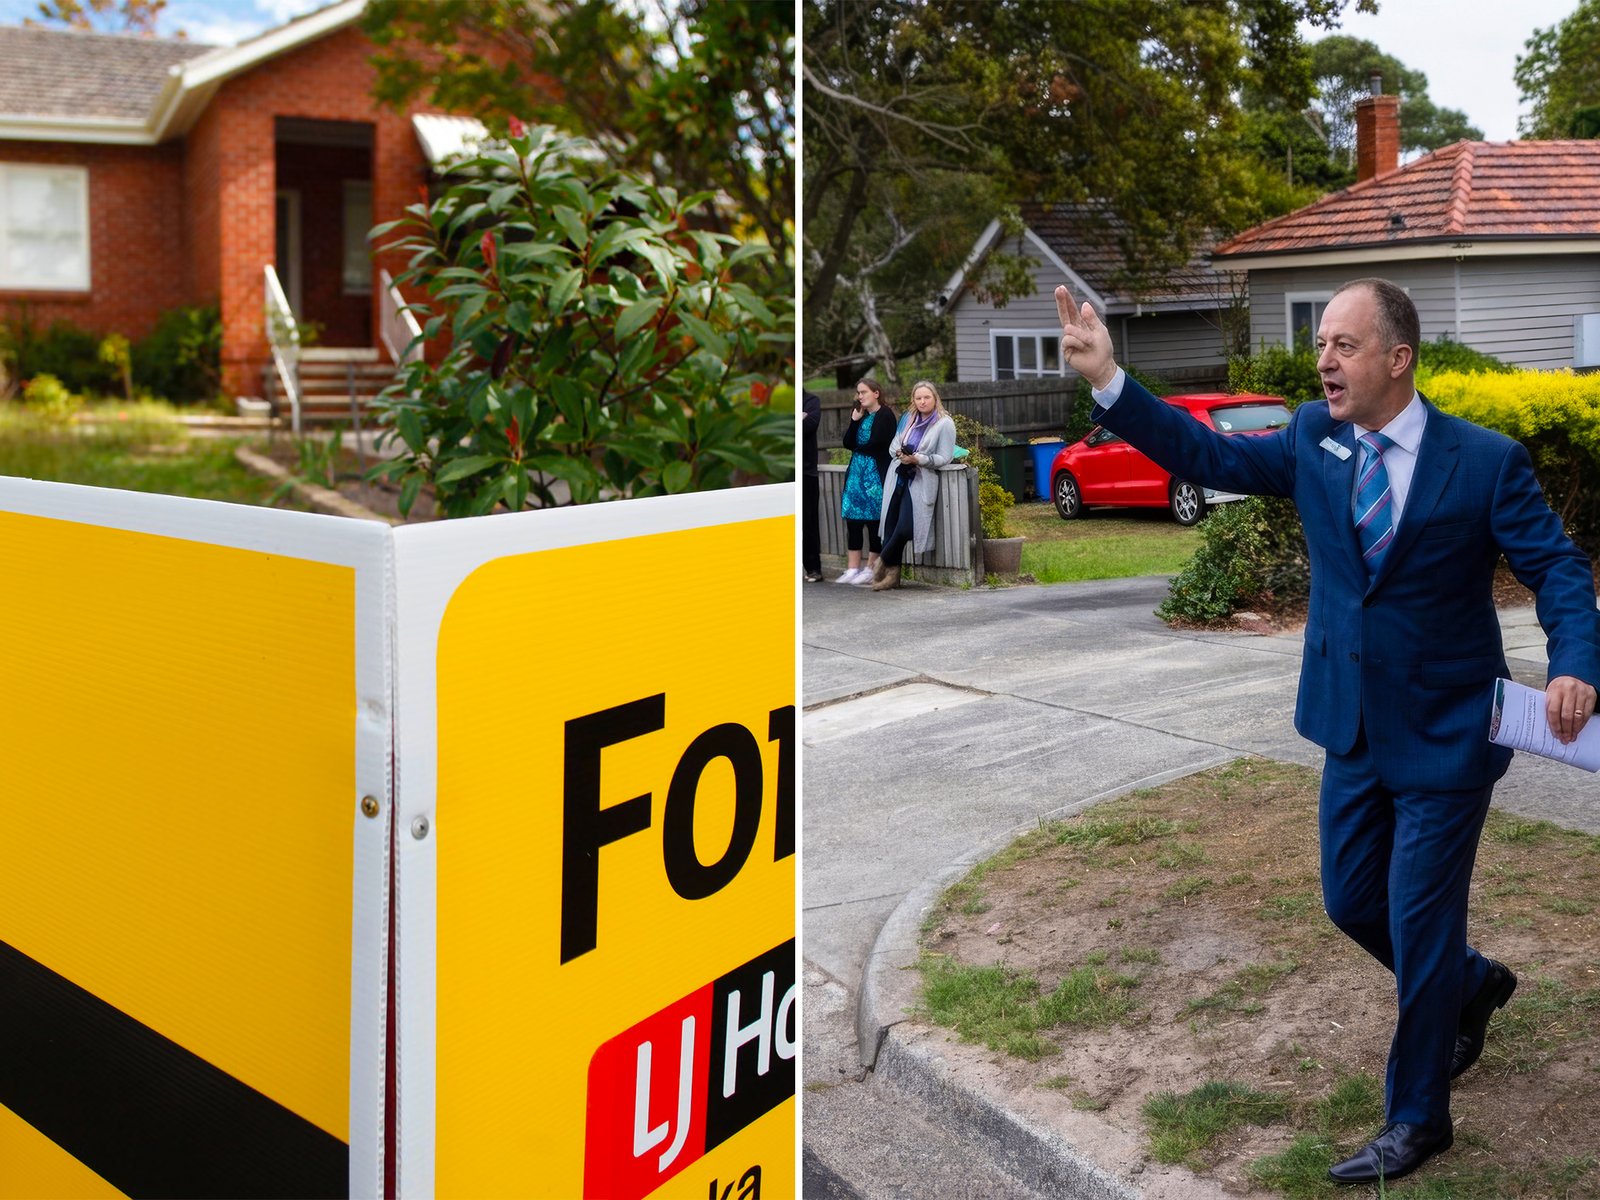
Victorians buying a home at auction can now see the seller’s reserve price at least seven days before the sale, under new transparency rules designed to curb underquoting. The requirements began applying to auctions and fixed-date sales held from 16 October 2026, following the introduction of the reforms on 1 October.
The reserve is the lowest price a seller is prepared to accept. Under the new rules, estate agents must ask sellers for the reserve in writing, publish it as a single dollar amount in property advertising and update marketing material once it is set. If the reserve has not been published for the full seven days, the auction or fixed-date sale cannot proceed.
The reforms also replace the old Statement of Information with a Property Price Statement. For residential properties advertised by an estate agent, the statement must include the property’s key features, information about comparable nearby sales and the suburb’s median price. Where three comparable sales cannot be identified, the agent must provide details of the one or two available and explain why more could not be found. Once a sale becomes unconditional, the final sale price must be published within seven days.
The changes are aimed at underquoting, which occurs when a property is advertised below the seller’s asking price, the agent’s estimated selling price or a price the seller has already rejected. Buyers have often complained that low price guides draw them into inspections and auctions for homes that ultimately sell for more than they expected to pay.
However, the reserve disclosure rules do not cover every type of sale. Consumer Affairs Victoria says they apply to residential auctions and fixed-date sales managed by estate agents. Private sales without a fixed deadline, commercial property sales and properties sold directly by an owner without an agent are outside these specific reserve-disclosure requirements.
Early signs suggest the rules could change how some properties are marketed. The Guardian reported that some agents were considering open-ended expressions of interest and private-sale campaigns, which do not have a fixed sale date and therefore do not trigger the same reserve-disclosure requirement. That is an emerging industry response, not evidence that the reforms have failed or that all agents are changing their approach.
There are also limits to what publishing a reserve tells buyers. The reserve is not a promise that the property will sell at that price: the seller retains the ability to reject a bid on auction day. The published figure gives buyers a clearer view of the minimum the seller says they will accept, while the Property Price Statement is intended to help them assess whether the advertised price is supported by comparable sales.
Melbourne auction activity fell sharply over the 17–18 October weekend, the first weekend when the new reserve-disclosure rules applied to auctions. But auction volumes alone cannot show whether the law caused the fall. Cotality, as quoted by The Guardian, said the drop could be a short-term disruption, with auction numbers rebounding for the following weekend. The market was also subdued, and auction activity can change with conditions and seasonal patterns.
The reforms are being watched beyond Victoria because auctions are common in Melbourne and Sydney, while private sales are more common in many other parts of Australia. Whether other states adopt similar rules will depend in part on how Victoria’s system works in practice, including whether price information improves and whether regulators can identify misleading price guides or attempts to avoid disclosure.
For buyers, the practical step is to check the Property Price Statement and the published reserve before committing time and money to an auction. If an advertised property appears to lack required comparable-sale information or its price details seem misleading, Consumer Affairs Victoria provides guidance on underquoting and property price statements.